There is a peculiar arithmetic at work in the Indian investor’s mind right now, and it has nothing to do with P/E ratios or earnings growth. It has to do with pain — specifically, the disproportionate pain of watching money disappear.
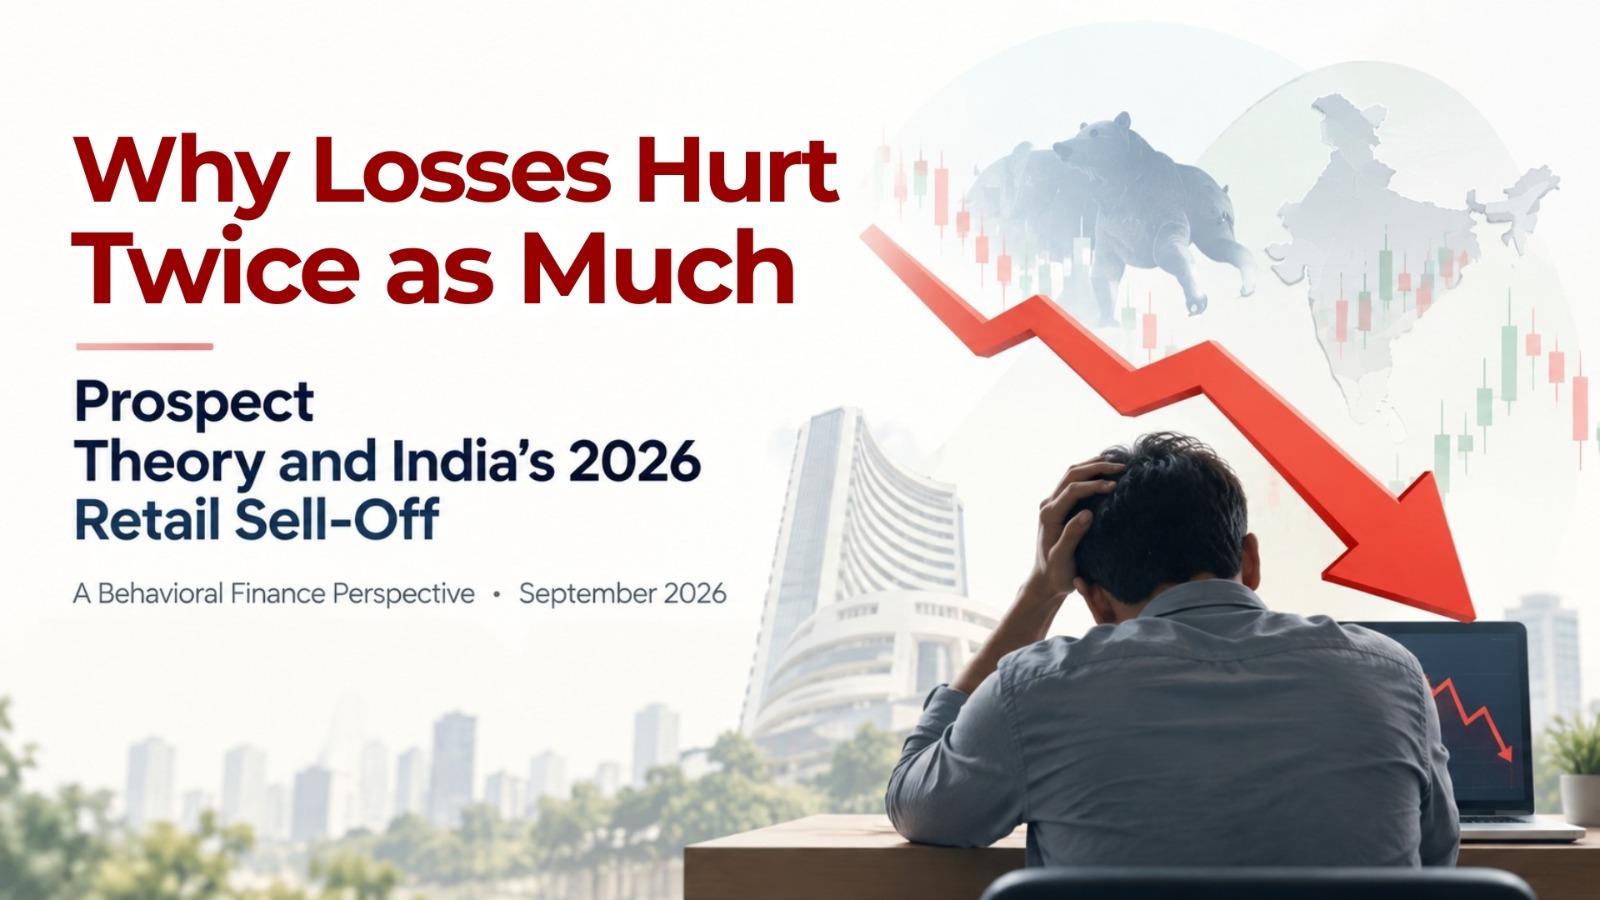
The data tells the story starkly. India’s benchmark Sensex is down roughly 3.78% over the past month and 10.48% compared to a year earlier, with sessions swinging on crude oil prices and Fed commentary, and analysts describing domestic sentiment as fragile beneath the surface [1]. Against this backdrop, individual investors have sold nearly ₹197 billion of local shares on a net basis this quarter alone — putting retail traders on pace for their biggest quarterly sell-off since mid-2023, as growth concerns and stretched valuations dent confidence [2]. This is a stunning reversal from barely a year ago, when retail ownership of NSE-listed companies touched a 22-year high [3].
Behavioral economists have a name for the mechanism behind this whiplash: loss aversion. But to really understand what’s happening — and why it happens so predictably — we have to go back to the theory it comes from.
The Architecture of Prospect Theory
In 1979, psychologists Daniel Kahneman and Amos Tversky published a paper that would eventually win Kahneman a Nobel Prize in Economics: Prospect Theory. Their central claim was radical for its time. Classical economics assumed investors evaluate outcomes based on final wealth — a rupee gained is worth exactly as much, psychologically, as a rupee lost is painful. Kahneman and Tversky showed this was simply false. People don’t evaluate wealth in absolute terms; they evaluate changes in wealth relative to a reference point — usually the price they paid, or the portfolio value they last saw at a comfortable high.
Around that reference point, the theory maps out what’s called a value function, and it has three defining features that explain almost everything about how real investors behave. First, it is defined over gains and losses, not final outcomes — so a portfolio at ₹9 lakh feels entirely different depending on whether it was ₹8 lakh or ₹11 lakh yesterday. Second, it shows diminishing sensitivity — the emotional difference between losing ₹10,000 and ₹20,000 feels much larger than the difference between losing ₹1,10,000 and ₹1,20,000, even though both gaps are identical in rupee terms. Third, and most consequentially, the function is steeper for losses than for gains — losses are felt roughly twice as intensely as equivalent gains. This asymmetry is loss aversion itself.
The real-world application of this is where prospect theory earns its keep, because it doesn’t just predict that losses hurt more — it predicts a specific, counterintuitive flip in how people take risk depending on which side of the reference point they’re standing on. When investors are sitting on gains, the theory predicts they turn risk-averse: they’d rather lock in a smaller certain profit than gamble for a larger uncertain one, which is why so many retail investors sell winning stocks too early. But when investors are sitting on losses, the same people turn risk-seeking: they’d rather gamble on the small chance of breaking even than accept a certain, smaller loss. This is why an investor who calmly booked profits on a stock that rose 15% will, weeks later, watch a losing position fall 30% and refuse to sell — not out of conviction in the company, but because prospect theory predicts exactly this reversal. The reference point — not the fundamentals — is doing the driving.
The Paradox Playing Out in Real Time
This is the paradox worth sitting with: loss aversion doesn’t produce one uniform behavior. Across India’s retail base today, it is producing panic at the portfolio level — investors exiting equities wholesale as the index slides [2] — while, stock by stock, it is producing paralysis in individual positions, where investors hold on to specific losing names long after the original investment thesis has broken down, hoping simply to “get back to even.” Both responses are wrong for the same reason. Neither is anchored to fundamentals. Both are anchored to an internal reference point — the price you paid, or the portfolio value you once saw — that the market has no obligation to honor.
Designing Around the Bias
The antidote isn’t willpower; it’s structure. Predetermined exit rules, position sizing decided before entry rather than during a drawdown, and a mechanical rebalancing discipline all work precisely because they remove the moment of decision from the moment of maximum emotional pain. You cannot out-think loss aversion in real time — the 1979 finding has survived nearly five decades of scrutiny for a reason. But you can design a process that never asks you to.
For India’s retail investor in September 2026, the most important number on the screen may not be the Nifty level at all. It may be the one measuring how much more a loss hurts than an equivalent gain feels good — and whether today’s decision is being made by that number, or in spite of it.
References
[1] HDFC Sky Markets Desk. “Indian Markets Set for Higher Open; Fed Decision in Focus.” September 16, 2026. hdfcsky.com
[2] Joshi, Ashutosh (Bloomberg). “Retail investors turn cautious as they dump stocks by most since 2023.” Business Standard. business-standard.com
[3] Business Standard. “Retail investors’ NSE market-cap share at 22-yr high of 18.75% in Q2FY26.” November 13, 2025. business-standard.com
[4] Trading Economics. “BSE SENSEX Stock Market Index.” Data as of September 17, 2026. tradingeconomics.com
[5] Kahneman, D., & Tversky, A. (1979). “Prospect Theory: An Analysis of Decision under Risk.” Econometrica, 47(2), 263–291.