There is a quiet contradiction sitting inside India’s personal finance data right now, and it says more about psychology than about economics. A recent industry survey found that 75.5% of Indians nearing retirement have no detailed financial plan for it — yet 61.4% of that same under-prepared group believe they will retire comfortably anyway [1]. The median retirement corpus Indians are actually sitting on is ₹28 lakh, against a realistic target of ₹1 crore — a shortfall of 3.6 times [1]. Confidence, in other words, is abundant. Planning is not.
This gap between how sure we feel and how prepared we actually are is not a quirk of the Indian saver. It is the signature of a very specific cognitive process — one that behavioral science has spent decades mapping.
Two Systems, One Decision
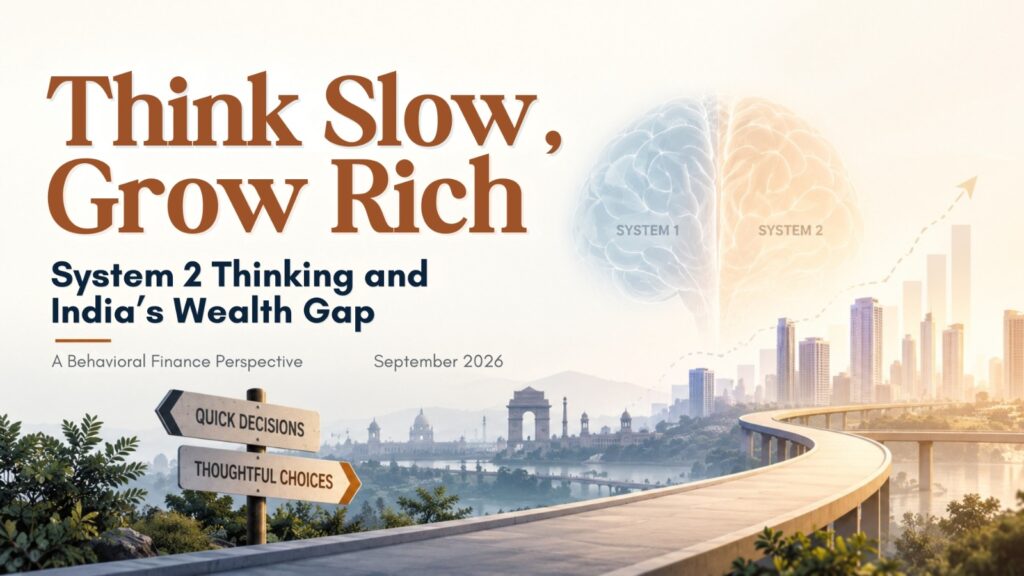
Nobel laureate Daniel Kahneman’s dual-process model describes the mind as running two distinct modes of thinking. System 1 is fast, automatic, and intuitive — it produces an instant feeling of ‘I’ll be fine’ without doing any arithmetic. System 2 is slow, deliberate, and effortful — it is the mode that actually sits down, calculates a retirement number, and works backward to a monthly savings figure. System 1 requires no energy and feels like certainty. System 2 requires real cognitive work and often feels, in the moment, entirely unnecessary — which is exactly why so many people skip it on the decisions that matter most.
Wealth creation is, almost by definition, a System 2 activity. It rewards patience over decades, deliberate trade-offs, and periodic recalculation as circumstances change. Left unchecked, System 1 quietly substitutes an easier question — ‘do I feel financially okay right now?’ — for the harder one a real plan requires: ‘will my current savings rate actually get me to my goal?’ The retirement confidence-planning paradox is what happens when an entire population answers the easy question and calls it done.
Where Else the Pattern Shows Up
The same substitution shows up well before retirement, in how a portfolio is actually managed. India’s mutual fund SIP stoppage ratio — the number of SIPs discontinued or matured against new registrations — stood at 81.1% in August 2026, and had crossed 100% earlier in the year, meaning more systematic investment plans were being closed than opened [2]. Analysts tracking the data note that stoppage ratios typically climb during market corrections, as investors react emotionally to short-term losses and abandon a discipline explicitly designed to work through volatility, not around it [3]. A SIP interrupted mid-cycle is a textbook System 1 decision dressed as prudence — it feels protective in the moment, while quietly shortening the compounding runway the entire strategy depended on.
A third, quieter example sits in how Indian household wealth is allocated in the first place. By one widely cited estimate drawing on RBI data, roughly 95% of Indian household wealth remains parked in physical assets such as gold and real estate, with only a small residual actively directed into financial instruments [4]. This allocation is rarely the product of a deliberate, comparative decision about risk, liquidity, and long-term return — it is closer to a cultural default, inherited rather than chosen. That is precisely the System 1 signature: not a wrong answer arrived at through reasoning, but the absence of the reasoning step altogether.
The Paradox Worth Sitting With
Three data points — the retirement shortfall, the SIP stoppage ratio, and the physical-asset skew — describe a single underlying failure mode, not three separate problems. Each is a moment where a slow, deliberate calculation was available and a fast, comfortable feeling was accepted in its place. None of these decisions feel irrational while they are being made; a paused SIP feels like caution, an under-planned retirement feels like optimism, and a gold-and-property-heavy portfolio feels like tradition. That is what makes System 1 so difficult to catch in real time — it never announces itself as a shortcut. It simply feels like a conclusion.
Designing for System 2
The fix is not more willpower; System 1 does not respond to willpower, because it does not experience itself as a choice at all. It is structure — a set of small, pre-committed rules that quietly stand in for System 2 at the exact moment System 1 would otherwise take over. A few that translate directly into practice:
Automate the decision out of the moment. SIPs, insurance premiums, and retirement contributions that debit automatically before money ever reaches a discretionary account require no willpower to sustain, because there is no daily choice left to make. The same logic applies to annual step-ups — pre-committing to increase SIP amounts by a fixed percentage each year removes the recurring, easily postponed decision to ‘revisit it later.’
Write the plan down, in numbers, once a year. A felt sense of ‘we should be fine’ is a System 1 verdict; a retirement number arrived at by working backward from a target corpus, expected inflation, and years to goal is a System 2 one. The specific act of writing it down — rather than estimating it mentally — is what forces the calculation to actually happen instead of being silently approximated.
Introduce a mandatory pause on reversals. A rule such as waiting seventy-two hours, or consulting one other person, before pausing a SIP, redeeming a long-term investment, or making a large discretionary purchase does not prevent the decision — it simply ensures System 2 is present for it. Most impulsive financial reversals do not survive a genuine cooling-off period intact.
Pre-commit to a rule for volatility, before volatility arrives. Deciding in advance — while calm — exactly what will and will not change about a portfolio during a market correction converts a stressful, in-the-moment judgment call into a simple act of following instructions already agreed to by a clearer-headed version of oneself.
Rebalance against a target, not a feeling. Periodically comparing actual asset allocation to a deliberately chosen target — rather than to how the portfolio has always looked — turns an inherited allocation into a reasoned one, and gives System 2 a concrete number to act on rather than an abstract sense that ‘this is just how it’s always been.’
Each of these works for the same underlying reason: they insert System 2 into the process before System 1 gets to act alone, at a point when the decision is calm, deliberate, and reversible — rather than during the exact moment it is neither.
India’s savers are not short on optimism. What the data suggests they are short on is the slower, less comfortable arithmetic that optimism alone cannot replace — and the gap between where most Indians are and where they believe they will end up is the cost of that missing calculation.
References
[1] Das, Basudha. “India’s retirement shock: 75% near age 60 lack a plan as savings fall 3.6x short of goal.” Business Today, May 20, 2026. businesstoday.in
[2] IndMoney Research Desk. “SIP Stoppage Ratio Was 81% in August 2026. Does That Mean 4 in 5 SIPs Were Cancelled?” 2026. indmoney.com
[3] Bajaj Finserv. “SIP Stoppage Ratio Explained.” 2026. bajajfinserv.in
[4] Marcellus Investment Managers. “The Big Shift in Small Town India” (analysis of RBI household wealth data). marcellus.in
[5] Kahneman, D. (2011). Thinking, Fast and Slow. Farrar, Straus and Giroux.